Bottom Line Up Front: Your shared coverage ends on your divorce date, not before. COBRA and Colorado’s mini-COBRA law let you keep your old plan for a price. Connect for Health Colorado gives you a 60 day window to shop the marketplace. Private PPO plans skip the waiting entirely, and that matters more than most people realize.
Your ex’s health plan stops covering you the moment your divorce is final. That single fact catches a lot of people off guard, especially after months of paperwork, court dates and moving boxes have already drained their energy.
Health insurance after divorce in Colorado does not have to mean a scramble. You have real options, and which one makes sense depends on your income, your ex’s employer size and how fast you need coverage in place. We’re the team at Colorado PPO Plans, a Colorado Springs brokerage that has spent since 2009 building direct carrier relationships with Aetna, Cigna and Anthem, the kind of access most Colorado agencies simply don’t have. Walk through the options below, and reach out when you’re ready to compare plans.
What Happens to Health Insurance After Divorce in Colorado
Once a judge signs your divorce decree, your ex’s employer plan will drop you as a dependent. Some plans end coverage on the last day of that month. Others cut it off within days of the decree, depending on how quickly the employer’s HR department processes the paperwork.
This is where a lot of the confusion around health insurance after divorce starts. Federal COBRA and Colorado’s state continuation law both call divorce a qualifying event, which lets you keep your existing group plan temporarily. The ACA marketplace calls it a qualifying life event instead, which opens a window to shop for a brand new plan. Those are two different systems with two different clocks, and knowing which one applies to you changes your entire strategy.
Private PPO plans skip this whole framework. There’s no qualifying event to prove and no clock running at all.
How Long Can You Stay on Your Ex-Spouse’s Health Insurance
The length of time you can stay on your ex’s plan comes down to the size of their employer. Two separate laws cover this, and most people have only heard of one.
Federal COBRA Eligibility and Cost
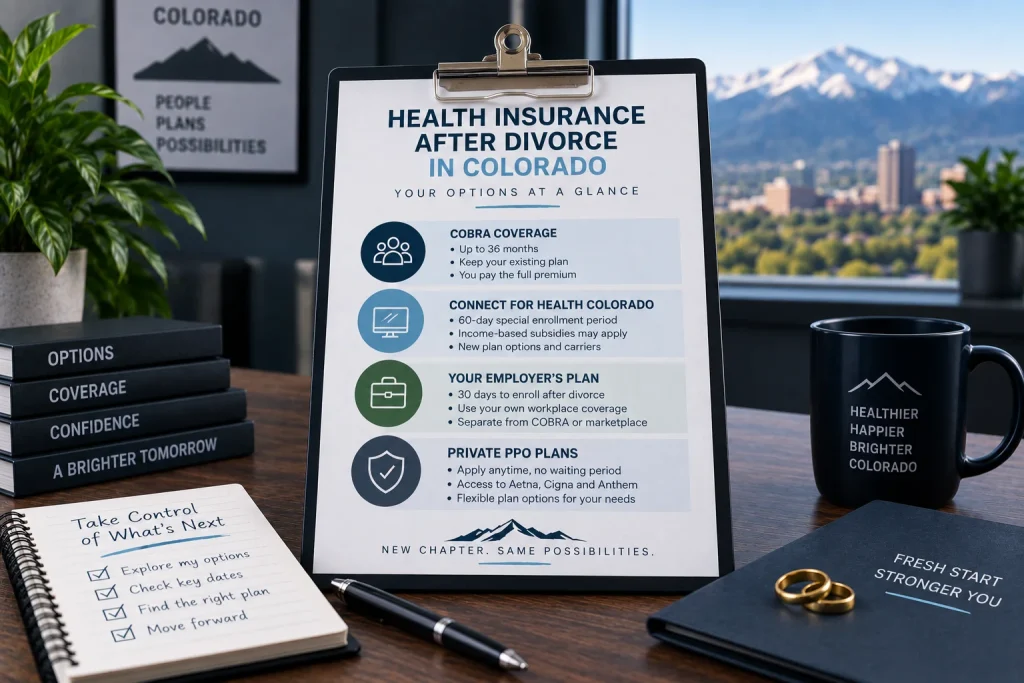
Federal COBRA applies once your ex’s employer has 20 or more workers. You get 60 days to elect coverage and 45 more days to pay your first premium after that. Divorce specifically qualifies for the full 36 month continuation window, not the shorter 18 months that applies to job loss, since losing coverage as a dependent gets treated differently than losing it as an employee.
The catch with COBRA after divorce is cost. You’ll pay the entire premium yourself, including the share your ex’s employer used to cover, plus an administrative fee on top. That typically lands somewhere between $600 and $1,200 a month depending on the plan and your household size.
Colorado’s State Continuation Law for Smaller Employers
If your ex works for a company with fewer than 20 employees, federal COBRA doesn’t apply, but Colorado still has you covered. State continuation coverage under C.R.S. 10-16-108 gives you up to 18 months on the same group plan, as long as you were continuously covered for at least six months beforehand. Most national guides to health insurance after divorce skip this entirely since it’s a state specific rule, but it’s often the only continuation option available if your ex worked for a small Colorado business.
Special Enrollment Periods for Health Insurance After Divorce in Colorado
If keeping your old plan through COBRA sounds expensive, and it usually is, the ACA marketplace is your next stop for health insurance after divorce. Connect for Health Colorado treats divorce as a qualifying life event, and this Colorado special enrollment period opens a real window to buy a new plan on your own terms.
Your subsidy eligibility resets based on your new household size and income, not your old joint return. That alone often makes marketplace coverage cheaper than COBRA, even without an employer contribution.
Connect for Health Colorado’s 60-Day Window
You get 60 days before your coverage ends and 60 days after to enroll, so you can line up new coverage before the old plan drops rather than scrambling afterward. Enroll in the first half of a month and coverage starts the first of the next month. Enroll in the back half and it starts the first of the month after that. Miss the window entirely and you’re stuck waiting for Colorado’s open enrollment period, which runs November 1, 2026 through January 15, 2027 for the coming plan year.
Adding Yourself to Your Own Employer’s Plan
If you have access to coverage through your own job, losing your spouse’s plan opens a special enrollment right there too, separate from COBRA or the marketplace entirely. The catch is timing. You only get 30 days to exercise this right under HIPAA rules, noticeably tighter than the 60 day windows above and easy to miss if you assume every deadline is the same length.
Private PPO Plans You Can Apply for Anytime in Colorado
Here’s the option most articles about health insurance after divorce never mention. Private PPO plans don’t require a qualifying event at all. You can apply any day of the year, divorce or no divorce, deadline or no deadline. Choosing private health insurance after divorce means skipping the whole qualifying event framework and enrolling whenever you’re ready.
This is exactly why we built Colorado PPO Plans around direct carrier access rather than a generic marketplace search. Our Anthem PPO plans and Aetna PPO plans give you the kind of provider choice a lot of Colorado agencies can’t offer, and you’re not boxed into a 60 day clock to get enrolled.
Why Apply-Anytime Coverage Matters After Divorce
Divorce already comes with more deadlines than most people can track at once. Court dates, asset division paperwork, custody filings and now an insurance clock too. Private PPO plans in Colorado remove one of those deadlines completely, which is a real relief when you’re already stretched thin.
Nationwide Coverage for Colorado Residents Who Relocate or Travel
Divorce often means a move, whether that’s across town or across state lines. Most private PPO plans travel with you nationwide, unlike marketplace plans that can restrict you to an in-state network. If your post-divorce life includes visiting kids in another state or relocating for a fresh start, that flexibility is worth weighing against a cheaper, more restrictive plan.
Comparing Your Coverage Options by Cost
Every option above trades cost against speed and flexibility. Here’s how they typically stack up, though your actual numbers will depend on your income, your plan and your carrier.
| Option | Typical Monthly | Best For |
| Federal COBRA | $600 to $1,200+ | Keeping your exact same plan and doctors short term |
| Colorado mini-COBRA | Similar to COBRA, often slightly less | Small employer situations where federal COBRA doesn’t apply |
| Connect for Health Colorado marketplace | $100 to $700+, subsidy dependent | Lower post-divorce household income |
| Private PPO plan | Varies by carrier and health history | Anyone who wants carrier choice without waiting on a deadline |
These figures are estimates, not quotes, so treat them as a starting point for your own comparison rather than a guarantee.
Should Health Insurance Be Part of Your Divorce Settlement
Health insurance costs are negotiable, and they belong in the settlement conversation just as much as the house or the retirement accounts. A judge can order one spouse to cover COBRA premiums for a set period, or the settlement can include a contribution toward a marketplace or private plan instead. That’s a conversation for your family law attorney, not us, but it’s worth raising early since it shapes which coverage option actually makes financial sense for you.
Consider Jenna, a hypothetical Lakewood resident who finalized her divorce in September after eleven years covered under her husband’s employer plan. Her attorney negotiated three months of COBRA premiums into the settlement to buy her time. By month two, Jenna had already compared her COBRA cost against a private PPO plan and switched over, since the private plan kept her preferred doctor in network for less than half the price. That kind of comparison only works if you know your options exist before the ink dries on your settlement.
Health Insurance for Your Children After a Colorado Divorce
Your kids generally don’t get dropped from coverage the way a spouse does. Most divorce decrees specify which parent carries the children going forward, and that parent’s plan typically continues covering them without interruption.
If the covering parent’s plan ends for any reason, the children qualify for their own 60 day special enrollment period, mirroring the rule for adults. If the other parent needs to add the kids to their own employer plan instead, that falls under the tighter 30 day HIPAA window covered earlier. For health insurance for children after divorce, a private PPO plan can also cover your whole newly restructured household under one policy, without tying enrollment to a qualifying event at all.
Health Insurance After Divorce if You Are Self-Employed or Own a Small Business
Self-employed Coloradans and small business owners often feel this loss harder than most, since there’s no employer HR department managing the transition and no group plan waiting in the wings. If you’ve relied on a spouse’s job for coverage while running your own business, this is one of the biggest financial surprises divorce can bring.
This is exactly the situation our self-employed health insurance and small business health insurance plans are built for. For self-employed health insurance after divorce, a private PPO plan often makes more sense than COBRA or a marketplace plan, since it gives you carrier flexibility without locking you into a renewal date tied to someone else’s job.
Get Covered with Colorado PPO Plans
Whichever path fits your situation, the goal is the same: no gap in coverage while you rebuild. We can walk you through COBRA, Colorado’s mini-COBRA law, the marketplace or a private PPO plan side by side.
We’re based in Colorado and built on carrier access most agencies don’t have. Contact us or call 719-435-4443 to talk through your options, or get a quote today and let’s get you covered.